
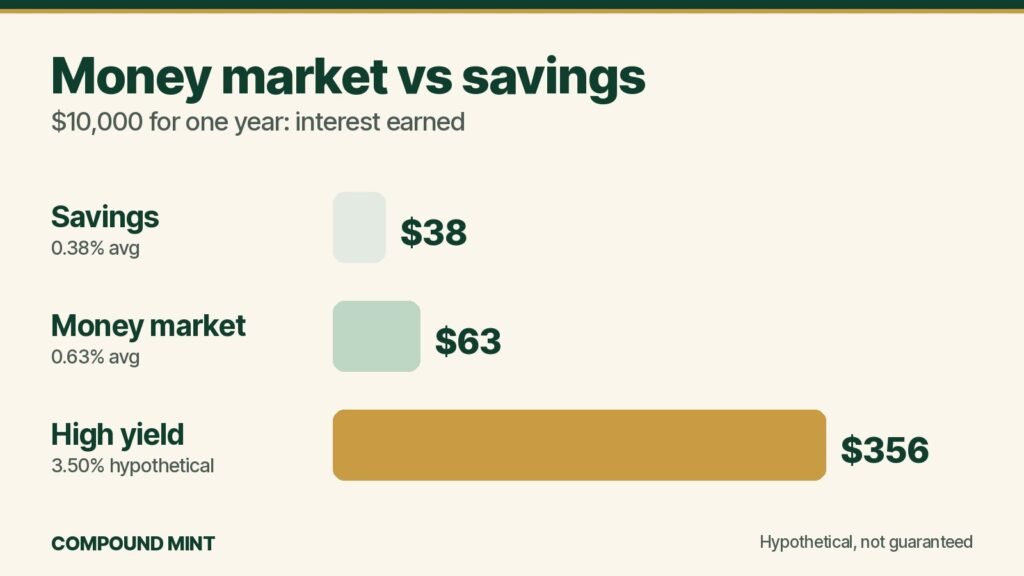
Short answer: A money market account is a bank savings account that usually pays a little more and lets you write checks or use a debit card, in exchange for a higher minimum balance. Both are FDIC insured up to $250,000. In October 2026 the FDIC’s national averages were 0.63% for money market accounts and 0.38% for savings, so on $10,000 that is about $63 a year versus $38. The bigger gain comes from picking a high yield account of either kind. Educational content only. Not financial advice.
The names make the choice sound bigger than it is. A money market account (MMA) is not an investment and it is not the stock market. It is a deposit account at a bank or credit union, insured the same way a savings account is. The real differences are access, minimum balance and the rate the bank chooses to pay.
Money market account vs savings account at a glance
| Feature | Savings account | Money market account |
|---|---|---|
| National average rate (FDIC, Oct 2026) | 0.38% | 0.63% |
| Minimum balance | Often low or none | Often higher; some banks pay more above set balance tiers |
| Access | Transfers, sometimes ATM | Transfers, plus checks or a debit card at many banks |
| Monthly withdrawal cap | Set by the bank, if any | Set by the bank, if any |
| Monthly fee | Common at big banks if you fall below a minimum | Common if you fall below the minimum |
| Insurance | FDIC (or NCUA at credit unions) up to $250,000 | FDIC (or NCUA at credit unions) up to $250,000 |
The rates come from the FDIC’s national rates as of October 19, 2026, which average savings at the $2,500 tier and money market accounts across the $10,000 and $100,000 tiers. The FDIC lists both savings accounts and money market deposit accounts as covered deposits. The old federal limit of six convenient withdrawals a month was removed by the Federal Reserve in April 2020, but many banks still set their own caps, so read the account terms.
Worked example: $10,000 in each account
Put $10,000 in and leave it alone. We compare the two national averages with a hypothetical 3.50% rate from an online bank, all compounded monthly, no deposits, no fees:
| Account and rate | Interest after 1 year | Balance after 5 years | Interest over 5 years |
|---|---|---|---|
| Savings, 0.38% average | $38.07 | $10,191.79 | $191.79 |
| Money market, 0.63% average | $63.18 | $10,319.93 | $319.93 |
| Online account, hypothetical 3.50% | $355.67 | $11,909.43 | $1,909.43 |
Switching from an average savings account to an average money market account adds about $25 a year on $10,000. Moving to a high yield account of either type adds about $300 a year. So the label matters less than the rate. Rates change often, and the 3.50% here is hypothetical, not guaranteed.
Run the 3.50% row yourself in the compound interest calculator, then swap in the rate your bank actually offers.
Assumptions: $10,000 deposited once, rates held constant and compounded monthly, no fees, before taxes. Interest is usually taxed as ordinary income. Examples are hypothetical, not guaranteed.
The fee trap
At the 0.63% average, $10,000 in a money market account earns about $5.25 a month. If the account charges a hypothetical $12 monthly fee whenever the balance dips below its minimum, three low months cost $36, more than half a year of interest. Before you open either account, check three things: the minimum to avoid the fee, the minimum to earn the top rate, and any cap on withdrawals.
Money market account vs money market fund
These sound alike but are different products. A money market account sits at a bank and is FDIC insured. A money market fund is a mutual fund you buy at a brokerage. Its yield moves with short term rates, and the SEC’s investor site notes that money invested in a money market fund is not guaranteed by the FDIC like bank accounts are. Funds can make sense for cash inside a brokerage account; here is how to open a brokerage account if you are starting from zero.
Which one should you pick?
- Pick a savings account if you are building a starter emergency fund, have a small balance, or want separate buckets for goals like sinking funds. Online high yield savings accounts often pay well with no minimum; see how high yield savings accounts work.
- Pick a money market account if you keep a larger balance, can stay above the minimum, and want to pay a big bill straight from savings by check or debit card.
- Either way, compare the actual rate and fees, not the account name, and keep the total at any one bank within insurance limits.
Weighing a CD instead? Our video CD vs HYSA: Which Pays More on $50,000? runs that comparison.
Educational content only. Not financial advice. Examples are hypothetical, not guaranteed. Rates and account terms change; check your bank’s current terms and the FDIC’s coverage rules for your situation.
Questions people ask
What is the downside to a money market account?
Money market accounts often require a higher minimum balance than savings accounts, and many charge a monthly fee if you fall below it. Some banks also limit how many withdrawals you can make each month. And while they usually pay more than an average savings account, many online high yield savings accounts pay as much or more with no minimum.
How much will $10,000 make in a money market account?
It depends on the rate. At the FDIC's October 2026 national average of 0.63%, $10,000 earns about $63 in a year. At a hypothetical 3.50%, it earns about $356 in a year and about $1,909 over 5 years with monthly compounding. Rates change, so these figures are hypothetical, not guaranteed.
Is a money market account better than a savings account?
Not automatically. A money market account usually pays a little more than an average savings account and may let you write checks, but it often needs a bigger balance. If you can keep that balance and want check access, it can be a good fit. Otherwise a high yield savings account with no minimum often does the same job.
Is a money market account FDIC insured?
Yes. The FDIC lists money market deposit accounts as covered deposits, up to $250,000 per depositor, per insured bank, for each ownership category. Credit union money market accounts are covered the same way by the NCUA. A money market fund at a brokerage is different: it is an investment and is not FDIC insured.
Can you lose money in a money market account?
Not from market swings, because a money market account is an insured bank deposit, not an investment. You can still lose ground to fees if you fall below the minimum, and to inflation if the rate is lower than rising prices. A money market fund, which is a mutual fund, is not guaranteed and can lose value.
Run the numbers yourself
Compound interest calculator
“$X a month for Y years”: see exactly what it turns into, with a chart you can share.
Open calculator →$1M or…? dilemma calculator
A lump sum today vs. payments over time (or a penny doubled). The channel’s signature question, with real math.
Open calculator →S&P 500 “what if I invested” calculator
What $100 a month in an S&P 500 index fund would have grown to, using honest historical averages.
Open calculator →